Health insurance is a system for pooling and managing the costs of medical care so that individuals aren't financially devastated by illness or injury.
It operates through contracts in which consumers pay premiums, and insurers agree to cover defined medical services. This industry exists to spread risk, stabilize healthcare financing, and ensure access to care.
Health insurance is a contract in which an insurer agrees to pay some or all medical expenses in exchange for regular premiums. It covers services such as doctor visits, hospital care, medications, preventative care, and specialized treatments.
The industry's core functions include risk pooling (spreading medical cost risk across large populations), underwriting and pricing (analyzing health risk and setting premiums), provider network management (negotiating rates with hospitals and physicians), claims processing (adjudicating and paying provider claims), and care management (wellness programs, chronic disease management, and utilization review).
The industry exists to protect individuals from catastrophic medical expenses, make healthcare financially predictable, improve access to preventative and routine care, and support public health through coverage of screenings, immunizations, and counseling.
Health insurance is a system for pooling and managing healthcare costs so individuals aren't financially devastated by illness or injury. It operates through contracts in which consumers pay premiums and insurers agree to cover defined medical services. This industry exists to spread risk, stabilize healthcare financing, and ensure access to care.
Most Americans receive private insurance through employer-sponsored plans in which employers negotiate group coverage, while employees pay part of the premium, or through individual marketplace plans purchased directly or through the ACA Marketplace.
Public insurance is comprised of government programs covering specific populations, such as Medicare (seniors 65+, certain disabled individuals), Medicaid (low-income individuals and families), CHIP (children in low-income households), and Veterans Health Administration (military veterans).
With self-insured employer plans, employers pay medical claims directly and hire third parties for administration (ASO arrangements).
Other types of insurance plans include short-term or limited-duration plans, which are temporary coverage with limited benefits, often used between jobs; and supplemental insurance, which includes policies such as critical illness insurance or accident insurance that pay lump sums for specific events.
Key terms in the health insurance industry incluse premium (monthly payment to maintain coverage), deductible (amount paid out-of-pocket before insurance begins paying), copayment (fixed dollar amount paid for specific services), out-of-pocket maximum (annual cap on what is paid), provider network (group of contracted healthcare providers offering discounted rates), claim (request for payment submitted by a provider to the insurer), open enrollment (annual window to sign up or change plans), qualifying life event (marriage, birth, job loss, or relocation allowing mid-year enrollment), reinsurance (insurance for insurers to protect against large losses), and FSA (employer-administered pretax account for medical expenses).
Designed to manage risks, finance healthcare, and protect individuals from high medical costs, health insurance operates through a structured value chain: underwriting, network contracting, claims processing, and care management.
Categories
Government Health InsurancePrivate Health Insurance |
Feature Article
ObamaCare: Love It Or Hate It
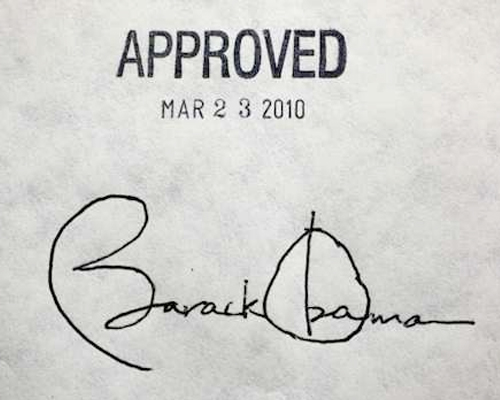
The Patient Protection and Affordable Care Act is also commonly known as
ObamaCare. The Affordable Care Act was signed into law by President Obama on
March 23, 2010 and later upheld by the Supreme
Court on June 28, 2012.
This law is one that most people either love or hate; the votes in both the
Senate and the House of Representatives were almost entirely on party
lines.
Those who love it point out these facts:
ObamaCare:
- allows adult children to stay on their parents' health insurance until they reach the age of 26;
- stops insurance companies from dropping insured people because of pre-existing conditions;
- subsidizes health insurance costs;
- mandates that most people buy healthcare insurance which complies with the federal government's "credible coverage;"
- gives all preventative and wellness services free of charge to those insured; and
- all insurance policies must have prescription drugs, emergency care, maternity, and neonatal care in order to be considered credible coverage; and
- everyone receives such benefits as perinatal, pediatric services, mental health and substance abuse services.
Amazingly, those who hate it point out the same facts!
They assert that the United States Constitution does not give the federal
government the power to mandate that Americans buy any product that they
don't want or feel they need, and they decry the new taxes
that the mandates carry with them.
While individuals are mandated to have coverage by 2014, a special exemption
was put into place last year which allows employers an extra year before
they have to offer it. Critics say that places an undue burden on the middle
class and the working
poor, many of whom are now left to find health plans on their own,
because they are required to obtain credible insurance coverage by 2014 or
get a waiver, or they will pay a "per-month" fee to the federal government.
The Affordable Care Act requires insurance companies which participate in
the marketplace to offer four new categories of insurance to consumers.
Those categories, from the lowest to the highest premiums, are called
Bronze, Silver, Gold, and Platinum Plans.
The Bronze Plan, which is described as having "essential health benefits,"
has the lowest premiums of these plans, but charge the highest out-of-pocket
costs. Those who opt for the Bronze Plan will pay 40% of their medical
bills, which is currently abnormally high co-insurance.
But more importantly -- and less understood by many who will be buying this
plan -- the average annual deductible is $5,081 for an individual and
$10,386 for a family.
What this means is that until the individual insured person pays $5,081 of
his own medical expenses, the insurance does not kick in. Those
out-of-pocket payments do not include premiums.
The average reasonably healthy person does not rack up that much in medical
bills in any one year, so many, if not most, people who buy the Bronze Plan
will be paying 100% of their own bills for their doctor's
visits.
Once these facts are realized by people, one would assume many would want to
leave the Plan, but that cannot be done mid-year; it can only be done during
the annual open enrollment period unless special circumstances are met, such
as moving
to an area where the existing plan does not have a network of providers.
On the other extreme, the highest premium plan is the Platinum Plan, which
has a $347 deductible for individuals and a $698 deductible for a family.
The average cost of a doctor
visit for Platinum Plan members is $16.00, and the insured is responsible
for only about 10% of the costs of their healthcare services.
Insurers are not mandated to offer the Platinum Plan, and it is believed
that most will not, as industry
analysts believe that this plan will attract people who are in ill health,
which would cost insurance companies large amounts of money, and since it is
now illegal to turn people down for insurance based on pre-existing
conditions, this could be financially disastrous for them.
The federal law requires all insurers who participate in the health
insurance exchanges to offer the two plans in between, the Silver and Gold
Plans.
The Silver Plan has an average individual deductible of $2,907 and family
deductible of $6,078, and the average primary care provider visit has a
copay of $32 per visit. The insured will pay 30% of the costs once the
deductible is met.
Those who choose the Gold Plan will pay 20% of covered healthcare expenses
after the deductible is met. The average deductible for this plan is $1,277
for individuals and $2,846 for a family; the average office visit with the doctor
is $24.
In the end, the success or failure of ObamaCare and the state health
insurance exchanges will not be known for a while, and in the meantime,
those that love the idea will continue to find its good points, while those
who do not will speak out against the bad points.
One thing is for sure: The unfolding will continue to be interesting to
watch.
Recommended Resources
This is a Medicare-focused lead generation site offering guidance on Medicare Part B premium avoidance strategies and dental insurance enrollment, rather than a traditional insurance carrier. Operating under the name "Alston Medicare," the platform is designed to collect user information, such as name, DOB, email, phone, address, and zip code, to deliver a Medicare Part B savings guide. Besides lead capture, the site provides information on enrollment timing, and dental insurance signups.
https://1800insurancect.com/
Headquartered in Hartford, Connecticut, and a subsidiary of CVS Health, Aetna is a managed health care company that sells traditional and consumer-directed health care insurance and related services, such as medical, pharmaceutical, dental, behavioral health, long-term care, and disability plans, primarily through employer-paid (full or partly) insurance and benefit programs, and through Medicare. Its plans may be reviewed on the website, along with other member resources.
https://www.aetna.com/
Anthem Blue Cross Blue Shield is one of the major U.S. health insurance carriers offering individual, family, Medicare, Medicaid, and employer health plans across many states. Anthem operates as an independent licensee of the Blue Cross Blue Shield Association, and provides medical, dental, vision, pharmacy, and employer group plans, as well as running the Sydney Heath app, the central hub for member benefits, claims, ID cards, and live chat. Eligibility can be determined online.
https://www.anthem.com/
Cigna is a major U.S. health insurer, the health insurance division of The Cigna Group, offering medical, dental, pharmacy, behavioral, and supplemental health plans for individuals, families, employers, and international customers. Its product line includes individual and family plans, employer-sponsored plans, dental, vision, and hearing bundles, supplemental coverage, and international health insurance. Plan shopping, a member guide, and approved doctors are set forth.
https://www.cigna.com/
HealthEquity and WageWorks have joined together to serve its combined employer clients through its Health Savings Account (HSA), Flexible Spending Account (FSA), Health Reimbursement Arrangement (HRA), COBRA, direct bill, commuter, fitness, and education reimbursement programs. An overview of the company, its clients, and consumer-directed benefits is set forth, and its leadership is introduced. Its products for individuals and businesses are featured, and contacts are provided.
https://www.wageworks.com/
Humana is a US-based for-profit insurance company based in Louisville, Kentucky, and the fourth-largest health insurance provider in the United States. Humana is a national health insurance company focused heavily on Medicare Advantage, Medicare Part D, individual dental/vision, and employer-based group benefits, and they operate through multiple subsidiaries depending on state regulations and product types. Its plans are defined on the company's website, along with information on Medicare.
https://www.humana.com/
Positioning itself as impartial, not an insurer and not a comparison site, myTribe is an independent, journalistic insurance information site focused on UK private health insurance, life insurance, and income protection. It produces guides, reviews, cost analyses, and news about private healthcare and insurance, acting as a broker-matching service; when a user requests a quote, myTribe connects them to the vetted broker partner, who forms its monetization; it is free to consumers.
https://www.mytribeinsurance.co.uk/
A major health insurance provider in New Zealand, the provider offers cover for individuals, families, employers, and visitors, and is part of the broader nib Group, which also operates in Australia. It offers health insurance, life and living insurance, travel insurance, health management programs, and a provider directory that helps users find doctors, specialists, and clinics in nib's First Choice network. Its products, coverage, health management programs, and a help center are included.
https://www.nib.co.nz/
One of the largest health insurers in the U.S., offering plans across Medicare, Medicaid, employer-sponsored coverage, and ACA individual/family markets, UHC is a national health insurance provider that sells and administers health plans, manages provider networks, and offers digital tools for members and clinicians, operating under the umbrella of UnitedHealth Group, a Fortune 5 company, offering Medicare Advantage, Medicaid, employer-sponsored, ACA Marketplace, and supplemental coverage.
https://www.uhc.com/